Inheritance Tax changes 2027: What they mean for your pension
Written: 22 October 2026. Last updated: 13 November 2026.
Key takeaways:
- Unused pension pots will be included in Inheritance Tax calculations from 6 April 2027.
- If you die at age 75 or over, your pension could also be subject to Income Tax when your beneficiaries withdraw funds.
- In some cases, including your pension in your estate could reduce the amount you can pass on tax-efficiently (known as your residence nil-rate band).
- You may be able to reduce your estate’s tax liabilities with careful estate planning.
From April 2027, the rules for passing on your unused pension funds are changing. With pensions set to be included in Inheritance Tax (IHT) calculations, your retirement savings could be taxed when they’re passed on to your beneficiaries. At the time of writing, they can be passed on tax-free.
In this article, we answer some of the most common questions you might be asking as the changes approach, and offer practical tips for managing the impacts on your pension and your estate.
What are the 2027 Inheritance Tax rule changes?
In the 2024 Autumn Budget, former chancellor Rachel Reeves announced that funds remaining in a pension on death will be included in the deceased’s estate for Inheritance Tax (IHT) purposes.
Previously, most unused pension funds and death benefits were excluded from estates for IHT purposes. As a result, some savers have used their pension as a tax-efficient means of passing on more wealth to loved ones.
However, from 6 April 2027, your pension pot could be liable for a 40% IHT charge when you pass away.
Will my pension pot be subject to Inheritance Tax?
While unused funds left in a defined contribution pension when you die will generally be included in your estate, that doesn’t necessarily mean they will be subject to Inheritance Tax (IHT).
IHT is only applied to the portion of your estate exceeding your nil-rate band. As of 2026/27, this is £325,000. You may also benefit from a residence nil-rate band of up to £175,000 if you leave your primary residence to a direct descendant.
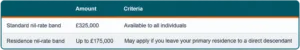
If you’re married or in a civil partnership, the surviving spouse may inherit their late partner’s unused nil-rate band.
So, a single person could pass on up to £500,000 before triggering an IHT bill, while a couple’s estate may not be taxed until the value passes £1 million.
If the total value of your estate – including your pension and any chargeable lifetime gifts or transfers – is less than your nil-rate band, your estate might not attract IHT. However, if your estate exceeds your nil-rate bands, the portion over the threshold will generally be taxed at 40%.
HMRC estimates that the inclusion of pensions in IHT calculations will see approximately 10,500 estates become subject to IHT for the first time in 2027/28, while 38,500 estates will face a higher IHT bill.
It’s important to note that assets passed to your spouse or civil partner are generally exempt from IHT. So, if you leave your pension to your partner, it may not be subject to IHT.
Read more: Why your pension could become liable for Inheritance Tax
What is the £2 million threshold for Inheritance Tax, and will my pension affect it?
In some cases, including your pension in Inheritance Tax (IHT) calculations could reduce your nil-rate band, meaning more of your non-pension estate is taxed.
The residence nil-rate band tapers from £175,000 once your total estate exceeds £2 million. You normally lose £1 of your residence nil-rate band for every £2 your estate exceeds the £2 million threshold. So, individuals lose their full residence nil-rate band if their estate is worth £2.35 million or over, while couples sharing nil-rate bands lose the tax-efficient allowance once their estate passes £2.7 million.
The bottom line is that if your pension pushes your total estate over £2 million, you could lose some or all of your residence nil-rate band.
Do beneficiaries pay Income Tax on pensions?
Depending on your age when you die, any pension pot remaining after Inheritance Tax (IHT) is applied could be subject to Income Tax when your beneficiaries draw the funds.
- Before age 75: Generally, your beneficiary won’t pay Income Tax when they take money from your pension pot, provided withdrawals don’t exceed the lump sum and death benefit allowance (£1,073,100 as of 2026/27).
- Age 75 and over: Your beneficiaries will typically be charged Income Tax at their marginal rate when they withdraw your pension funds. Note that the withdrawals will count as income and could push your beneficiaries into a higher tax bracket.
As it stands, these rules will remain in place after 6 April 2027.
Ultimately, this could mean your unused pension funds are taxed twice – with IHT charged first, followed by Income Tax as your beneficiary withdraws the remaining amount.
Depending on your age at death, the amount left in your pension, and your beneficiary’s other income, this could mean up to 67% of your pot goes to HMRC.
How can I reduce my estate’s Inheritance Tax bill?
While you can’t change the new legislation coming into effect from April 2027, you can take action to shield your wealth – including your pension – from Inheritance Tax (IHT).
Naturally, the appropriate steps will depend on your unique circumstances, but you might consider:
- Gifting wealth in your lifetime: Passing wealth to loved ones during your lifetime could reduce the size of your estate, and therefore your IHT bill. However, some gifts may be taxable. Read more: 4 HMRC-approved gifting strategies to cut your Inheritance Tax bill
- Spending your pension before other income sources: If you’re concerned about your pension being subject to both IHT and Income Tax, it may be worth tax-efficiently decumulating your pension pot before spending funds from other income sources. That said, rushing to access your pension could have a negative impact on your retirement. Read more: 5 questions to answer before you withdraw a pension lump sum to reduce Inheritance Tax
- Putting life insurance in trust: While life insurance generally won’t reduce your estate’s IHT liability, suitable cover could help your loved ones pay the bill without using assets within your estate – such as your pension. By placing the policy in trust, you could avoid the payout being included in your estate’s value and help your beneficiaries receive the payment sooner.
- Leaving a charitable legacy in your will: Typically, leaving 10% or more of your net estate to charity can reduce your IHT rate from 40% to 36%. Remember, after 6 April 2027, the value of your pension will be included in your estate, so be sure to make suitable provisions in your will if you’re hoping to lower your IHT rate.
It’s important to note that spending or gifting too much could leave you short of your financial goals later in life. A financial planner can support you in defining a strategy to mitigate IHT, while ensuring you have enough to meet your current and future needs.
Read our Guide to Estate Planning
Speak to a financial planner
At Fiducia Wealth, our chartered financial planners can help you understand how the upcoming changes to IHT and pensions could impact your estate. Working closely with you to understand your needs, goals, and circumstances, we can create a strategy to mitigate your estate’s tax liability.
Email us at email@fiduciawealth.co.uk or call us on 01206 321 045 to find out how we could support you.
Want to learn more about working with Fiducia? Discover 5 important reasons why over 90% of our clients recommend us
Please note
This article is for general information only and does not constitute advice. The information is aimed at individuals only.
All information is correct at the time of writing and is subject to change in the future.
Please do not act based on anything you might read in this article. All contents are based on our understanding of HMRC legislation, which is subject to change.
The Financial Conduct Authority does not regulate estate planning, tax planning, trusts, or will writing.
A pension is a long-term investment not normally accessible until 55 (57 from April 2028). The fund value may fluctuate and can go down, which would have an impact on the level of pension benefits available. Past performance is not a reliable indicator of future performance.
The tax implications of pension withdrawals will be based on your individual circumstances. Thresholds, percentage rates, and tax legislation may change in subsequent Finance Acts.
Note that life insurance and financial protection plans typically have no cash in value at any time and cover will cease at the end of the term. If premiums stop, then cover will lapse.