Savings & Investments – What you need, Why & How
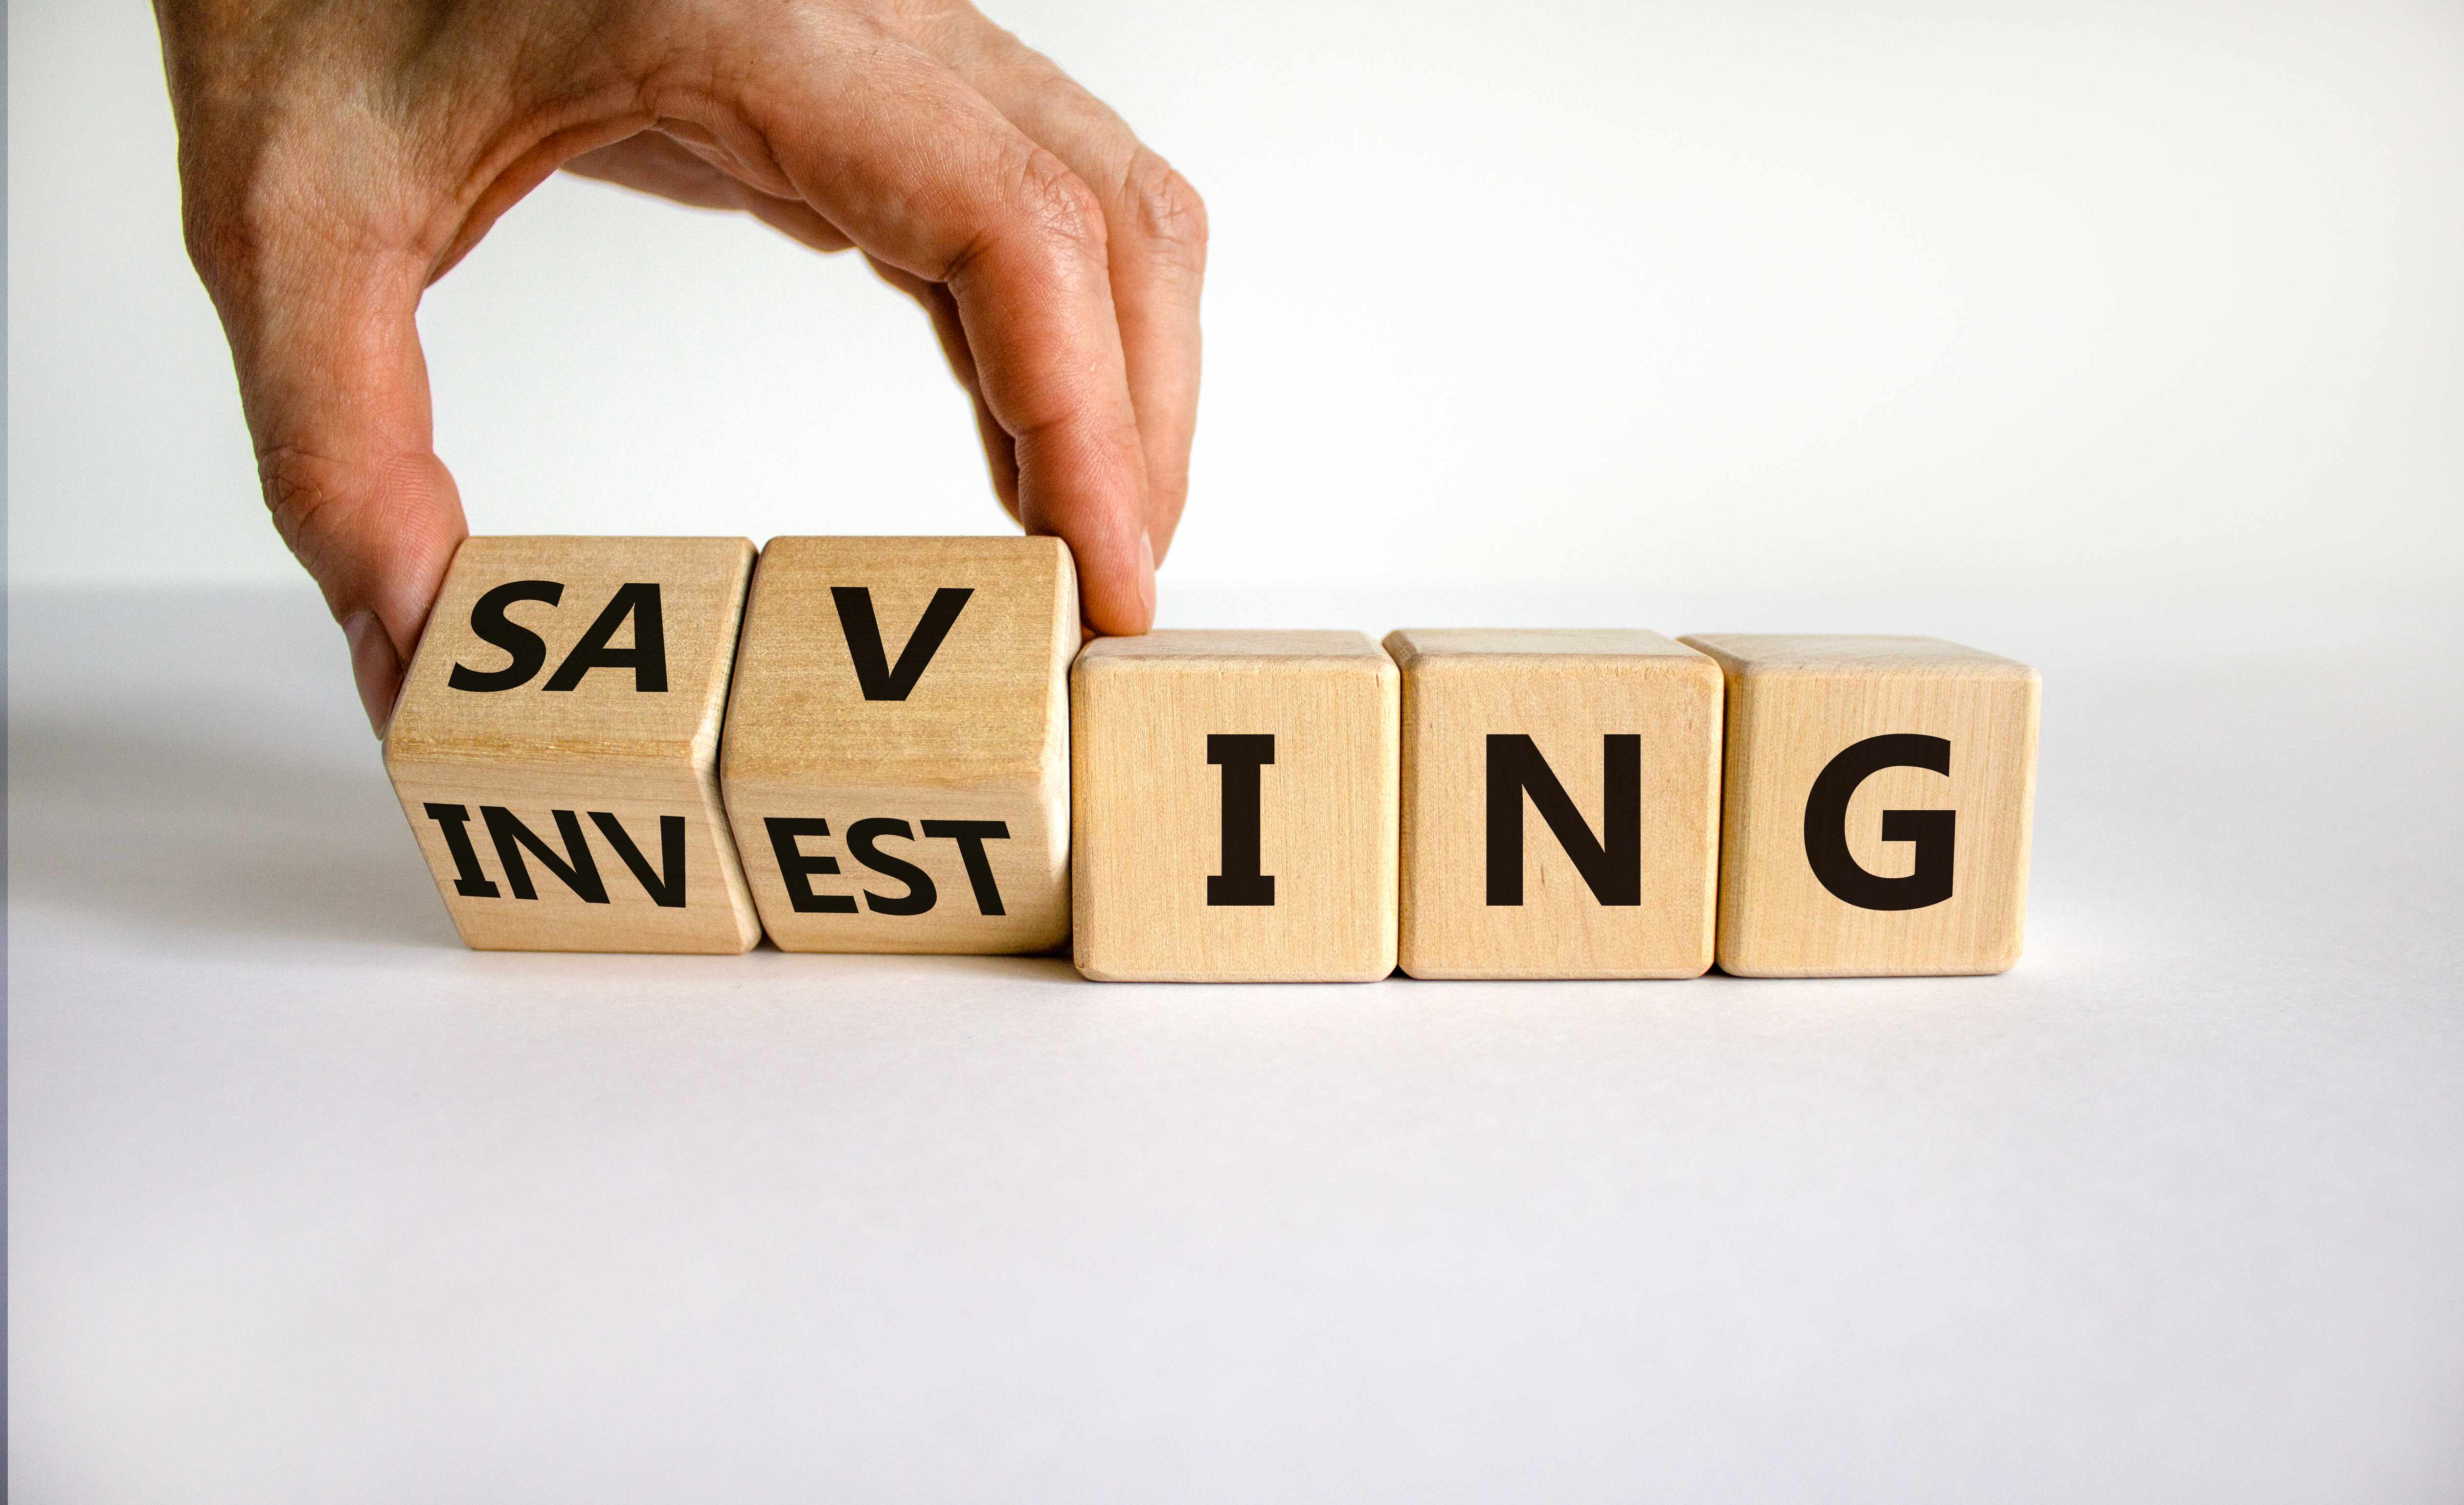
Savings and Investing are often are used interchangeably, but there is a difference. What are they? Why are they helpful? And how can they benefit you?
This is an area that truly merits taking professional advice, but it’s very important to have a grasp of both areas, and their differences, before considering them for yourself.
Saving is setting aside money you don’t spend now for emergencies or for a future purchase. It’s money you want to be able to access quickly, with little or no risk, and with the least amount of taxes. Financial institutions offer a number of different savings options.
Investing is buying assets such as stocks, bonds, mutual funds or real estate with the expectation that your investment will make money for you. Investments usually are selected to achieve long-term goals. Investments can be categorised as income investments or growth investments.
Making a choice between either saving or investing will depend on your goal(s) and your risk tolerance, which is the first step a good financial adviser will take with you after a fact find
Determine Your Risk Tolerance
You need to understand how much risk you’re willing to take and which types of risk most worry you. Your risk tolerance (the degree of uncertainty you are willing to take on to achieve potentially greater rewards) is determined by a combination of factors, including your investment goals and experience, how much time you have to invest, your other financial resources and your “fear factor.”
How Do You Beat Inflation?
When it comes to building wealth, time is much more powerful than the amount you invest or even the returns you earn. But it also matters where you put your money. Simply put, investing fights inflation: the same items you purchase today will cost more in the future.
With savings rates being low, it is rather difficult to achieve positive returns over inflation. Investing on the other hand, depending on your anticipated time horizon and risk profile, can provide opportunity to make more positive returns. This can also lead to more potential tax implications; it is important to understand what these implications are before you begin investing.
Inflation and the Time Value of Money
Most people know that £100 today probably will not buy the same amount of goods that £100 will buy next year, but few are sure how investing will help.
Investing takes advantage of compound interest over time, so the more time you invest — in general — the more opportunity your money has to grow.
How long are you planning to invest for? Which product/wrapper is suitable for you? How much risk are you willing to accept? How can you invest in a tax efficient way? These are all questions which you should consider and discuss with a professional.
The Magic of Compounding Interest

The more frequently your money earns interest, the faster and bigger your balance will grow. As interest is added to your account, you earn interest on the original balance, plus the previously earned interest.
The final return on your money is called the Annual Percentage Yield (APY).
When interest is compounded, the amount paid in a year is more than the simple interest rate that is given. Financial institutions show the return as the APY — the actual return on an investment when compound interest is considered.
What Should You Invest in?
Most stocks are examples of growth investments that you buy in hopes of selling for a higher price later. But there are other types of investments, including real estate (your home, commercial property), precious metals (such as gold) and energy (such as oil and gas). Some investments, such as rental property and fixed-income securities (such as government bonds), are not meant to be sold, necessarily, but are meant to be maintained as a consistent source of income.
There are also tax efficient wrappers available that allow you accrue Capital Gains and Income in a tax efficient way. With so many tax efficient wrappers available, we recommend you take time to understand which ones better suit your financial needs. Financial planning includes identifying which tax efficient wrappers better suit your needs. A meeting with a financial adviser will explore this.
The primary goal of growth investments is to sell the assets at a higher price than you paid for them. Some investments qualify as both growth and income investments. Compared to income investments, growth investments typically offer more potential for bigger gains … and losses.
Alternatively, income investments provide regular earnings such as monthly interest, quarterly dividends or even rent payments. Steady, predictable income is the goal for income investments. Choose wisely to create a balanced portfolio.
Long term planning
It’s critical to think further than tomorrow, next week or next month where financial planning is concerned. In fact, if you speak to most financial advisers, the conversation will start with the anticipated time horizon in years, not days, weeks or months.
Therefore, understanding what your future financial needs are and ensuring they can be met is critical when investing for the medium to long term. Identify what your risk profile is and speak to professionals to understand how that changes throughout your life.
Before you begin to research your investment strategy, it’s important to gather some basic information about your financial situation. In your fact find session, you will want to consider these key questions:
- What is your current financial situation?
- What is your cost of living including monthly expenses and debts?
- How much can you afford to invest—both initially and on an on-going basis?
Even though you don’t need a lot of money to get started, you shouldn’t get start if you can’t afford to do so. If you have a lot of debts or other obligations, consider the impact investing will have on your situation before you start putting money aside.
Investing is a long game. Whether you want to invest for retirement or grow your savings, it’s best when you put money to work in markets and set it and forget it. But successful long-term investing isn’t as simple as just throwing money at the stock market, it requires a rational head and a willingness to consider the future, with an element of flexibility. It is often as much a question of what you don’t know as what you do.
For a no obligation discussion about your savings and investment goals or to review your existing portfolio, contact a member of our team today.